Mortgage Rates & Affordability: What Buyers Face Right Now
Mortgage rates matter—but the better homeowner question is whether the total payment fits your life, your cash reserves, and the specific home’s value. A lower rate can improve affordability. It cannot fix an overpriced home, weak inspection results, thin savings, or a payment that crowds out everything else.
Start With the All-In Payment
Do not shop by listing price alone. Build a monthly payment for each serious property:
- Principal and interest - Property taxes - Homeowners insurance - Mortgage insurance, if applicable - HOA or condo fees - Expected maintenance reserve - Any flood, wildfire, or other location-specific insurance cost
Then test the payment against a realistic household budget—not just the amount a lender may approve. Include commuting, child care, debt payments, upcoming repairs, and the cash you want left after closing.
A useful rule: compare the payment at today’s quoted rate with a higher-rate scenario. If the deal works only under the most favorable quote, it is fragile.
Read Rates as a Range, Not a Headline
Freddie Mac’s Primary Mortgage Market Survey archive provides historical context for conventional mortgage rates. Use it to understand direction and volatility, but get actual lender quotes for your own decision.
Your rate will depend on factors such as:
- Credit profile - Loan type and term - Down payment - Occupancy and property type - Loan size - Discount points and lender fees - Debt-to-income ratio
Two buyers can pursue the same house and receive materially different offers. Ask lenders for standardized Loan Estimates, compare the annual percentage rate and closing costs alongside the interest rate, and confirm how long a rate lock lasts.
Affordability Is Also About Available Choices
Market conditions affect your leverage after you qualify.
Census reported that new single-family home sales ran at a seasonally adjusted annual rate of 684,000 in August 2026. Its new residential construction release reported privately owned housing units authorized by building permits at a 1.394 million annualized rate that month. Those national figures do not tell you what is available in one neighborhood, but they help frame the supply side of the market.
For local conditions, check active listings, price reductions, days on market, concessions, and recently closed comparable sales. Zillow Research and Redfin’s housing market data can be useful market-level starting points. Treat them as context; verify a property-specific decision with local listings and completed sales.
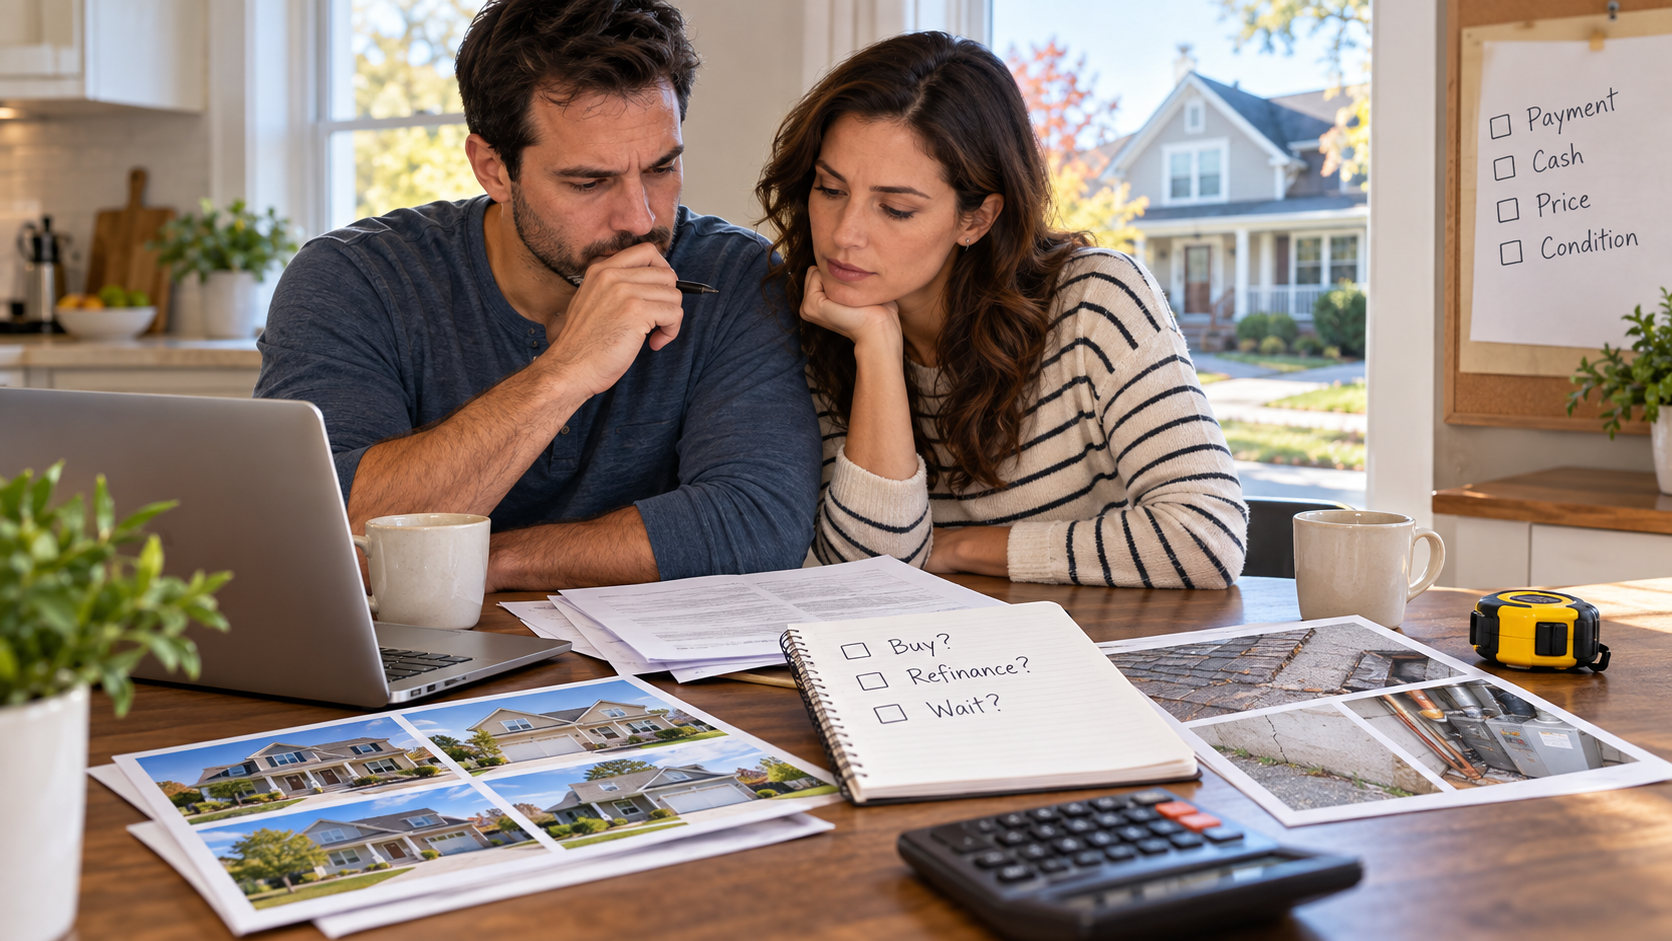
Choose the Right Decision: Buy, Refinance, or Wait
Buy when the house and payment both work
Buying may be reasonable when you expect to stay long enough to absorb transaction costs, can cover closing costs and reserves, and can afford the payment without assuming a future refinance.
Focus on the home’s condition and comparable sales. A modest seller credit, repair concession, or price adjustment may matter more to your immediate finances than trying to predict the next move in rates.
Refinance when the numbers—not the headline—justify it
A refinance replaces one loan with another and comes with costs. Compare:
1. Your current all-in mortgage payment. 2. The proposed payment, rate, term, and cash required at closing. 3. The breakeven period: closing costs divided by monthly savings. 4. The total interest and remaining balance under each loan.
A lower payment can result from extending the loan term, not simply from a better rate. Make sure you understand what changes before proceeding.
Wait when the decision needs a stronger foundation
Waiting can be sensible if the payment strains your budget, your down payment would drain reserves, the property has unresolved condition issues, or comparable sales do not support the price.
Waiting is not a forecast on rates or home values. It is a decision to improve your position: save reserves, reduce debt, strengthen credit, learn local pricing, and revisit homes that meet your criteria.
Use a Four-Check Property Test
Before making an offer or refinancing decision, answer four questions:
1. Payment: Can we afford the full monthly cost under a less favorable rate or expense scenario? 2. Cash: Will we retain enough funds for closing, moving, repairs, and emergencies? 3. Price: Do recent, nearby comparable sales support the purchase price? 4. Property: Do public records, permits, taxes, insurance requirements, and inspection findings match what is being marketed?
Mortgage rates are one input. Payment durability, property condition, and verified local value are the decision system.
Before you buy, refinance, or wait, use PropertyDeepDive to check public records, confirm property details, and review comparable sales before making a property decision.